
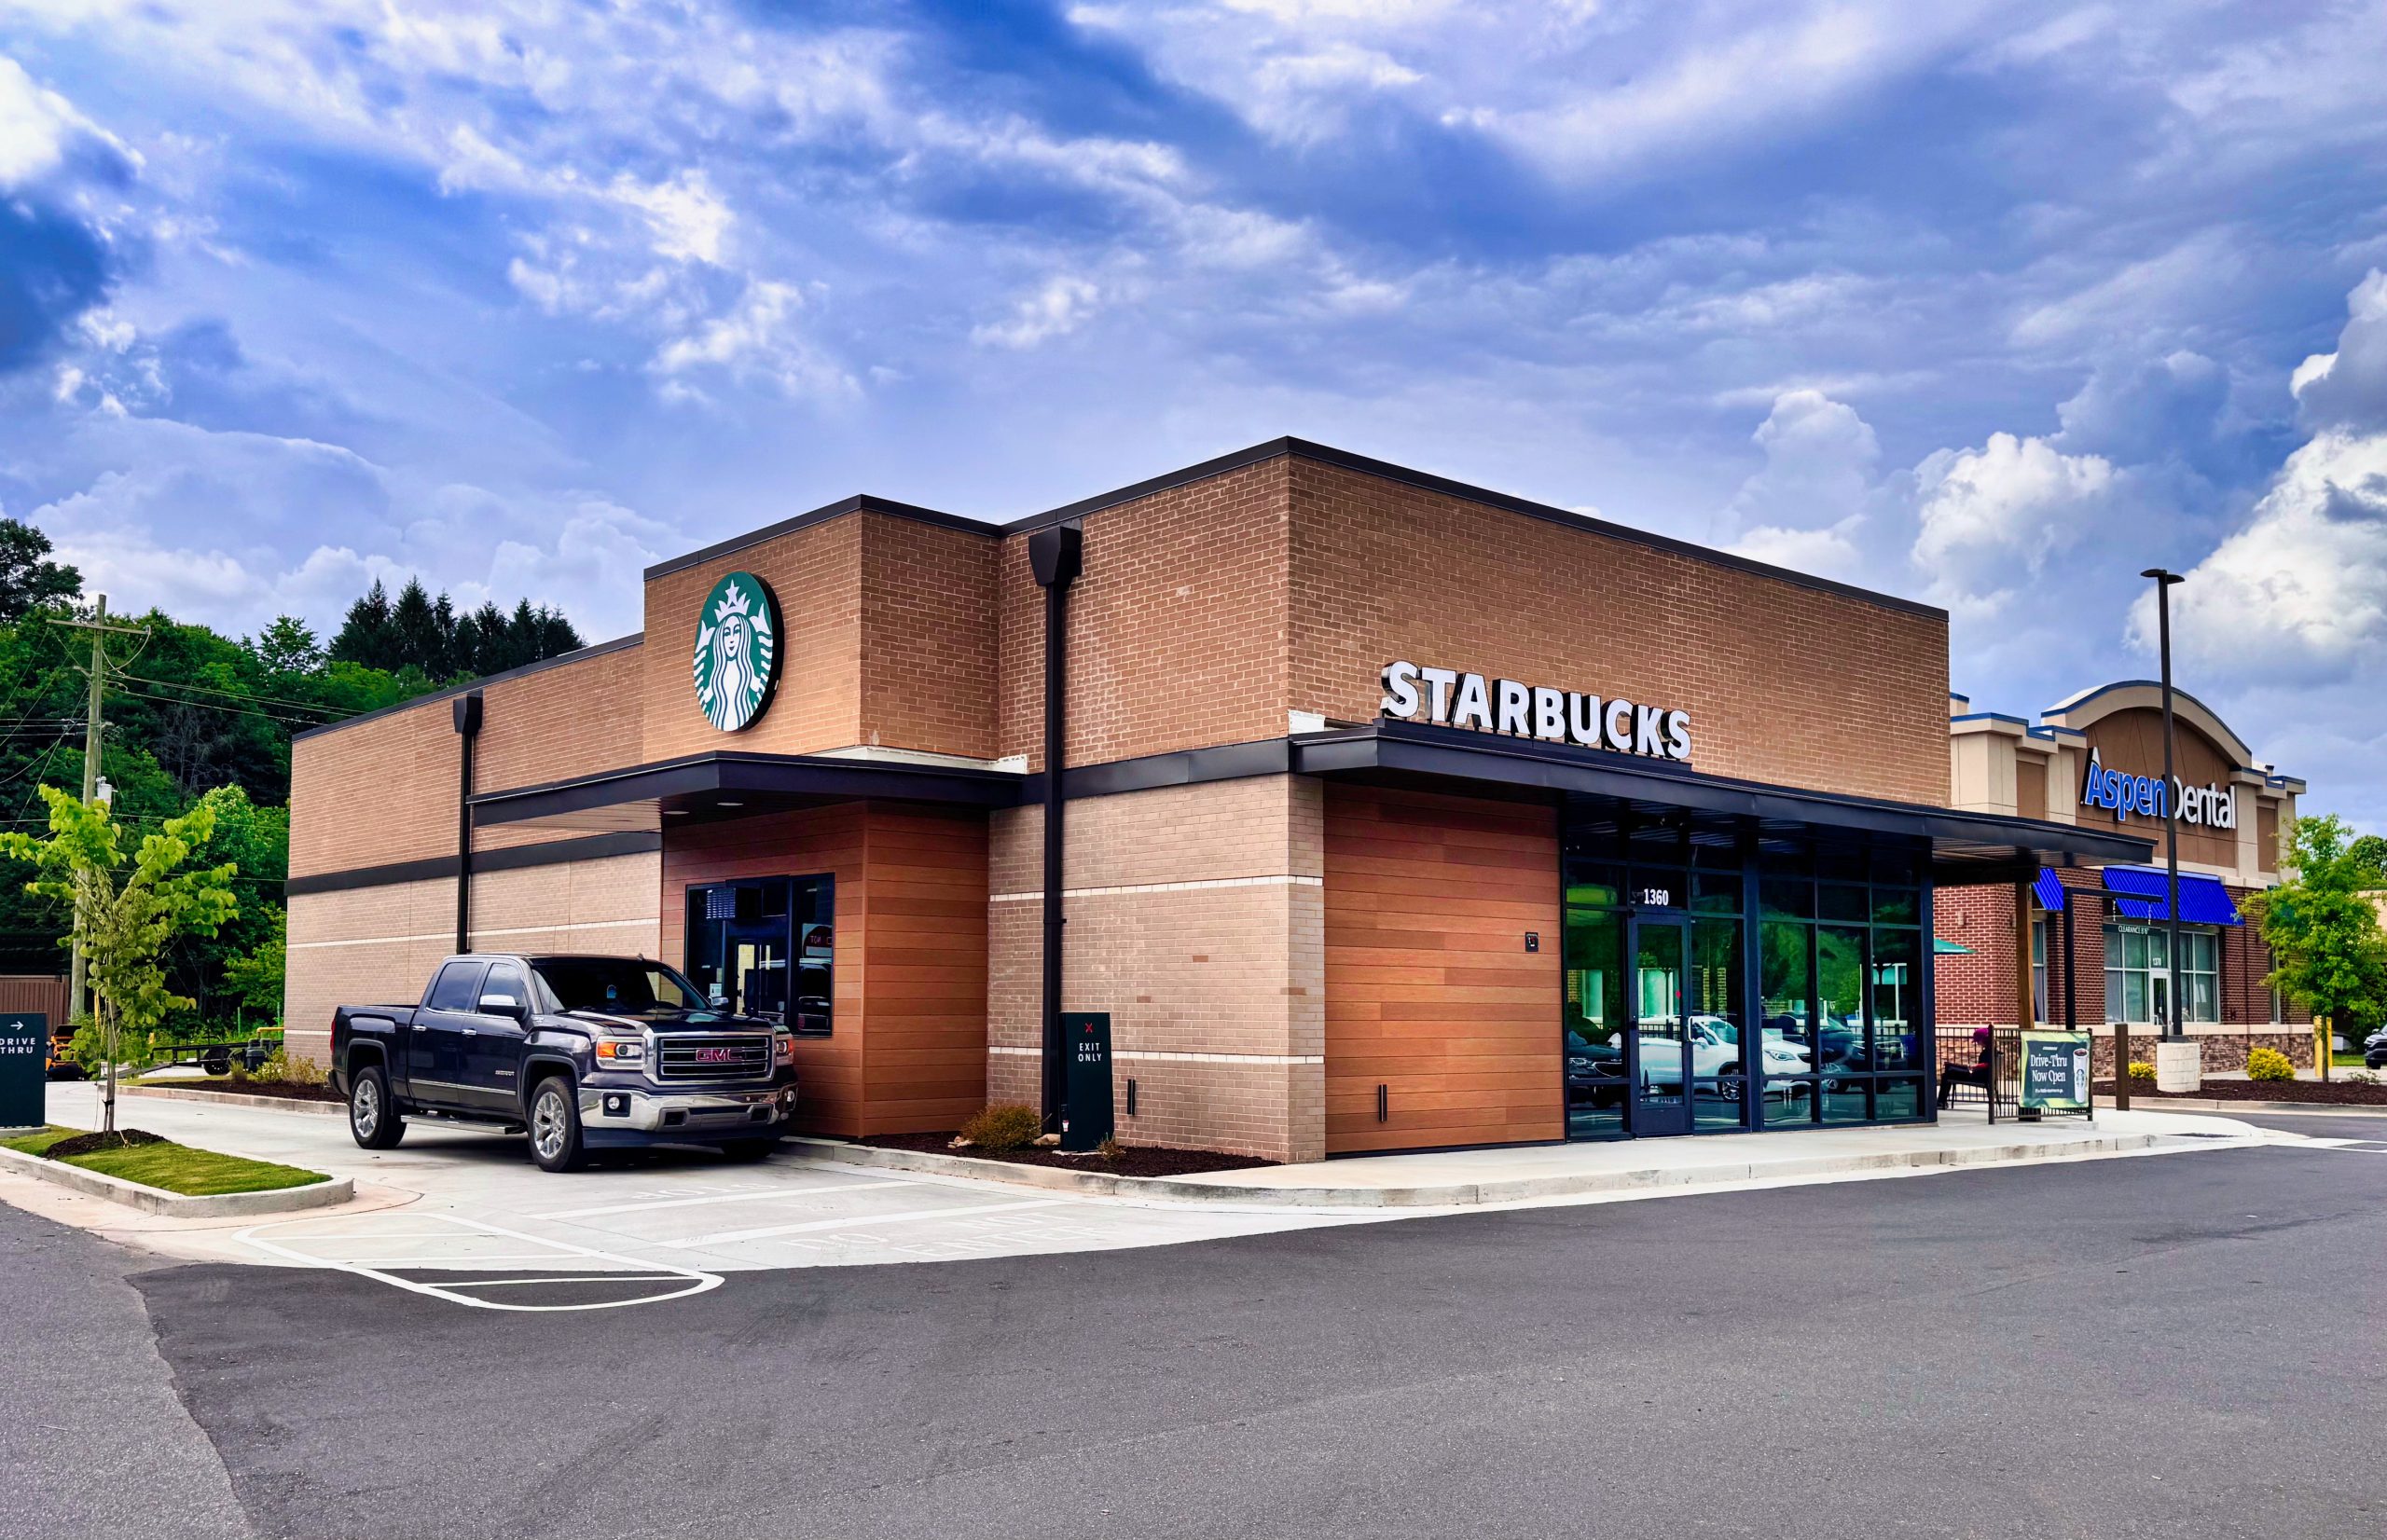
Looking to buy a Starbucks NNN property? 124 are observed for sale across 35 states, median asking cap rate 5.75%. View Starbucks NNN properties for sale, cap rate bands and the 1031 buyer guide.
| Metric | Details |
|---|---|
| Parent Company | Starbucks Corporation |
| Credit Ratings | S&P: BBB+ / Moody’s: Baa1 |
| Rated Entity | Starbucks Corporation |
| Rating Source | S&P Global Ratings BBB+, as of May 6, 2025; Moody’s Baa1, as of May 6, 2025. Ratings checked October 8, 2026. |
| Sector | QSR |
| North American Locations | ~18,400 (11,149 company-operated, 7,222 licensed; June 28, 2026) |
| Median asking cap rate | See the live table below |
| Lease Term | Varies; confirm the term and any renewal or termination options in the lease |
| Guarantee Type | Varies; confirm the tenant entity and any Starbucks Corporation guaranty in each lease |
| Stock Ticker | SBUX (NASDAQ) |
| Annual Revenue | $37.2B (fiscal 2025) |
| Asking Price (listings we track) | $2.40M to $3.28M (middle half; median $2.84M) |
Bond vs NNN Comparison: See how Starbucks corporate bond yields compare to Starbucks NNN cap rates, with after tax math, depreciation impact, and 1031 exchange treatment. Starbucks Bonds vs NNN →
Starbucks Business Overview & NNN Investment Grade Profile
Starbucks describes itself as the premier roaster, marketer and retailer of specialty coffee globally, and it had about 18,400 North American stores (roughly 11,100 company-operated and 7,200 licensed) as of June 28, 2026 (Form 10‑Q). Under CEO Brian Niccol (since September 2024), Starbucks is executing its “Back to Starbucks” turnaround, which focuses on the coffeehouse experience, its Green Apron Service standard, menu discipline, a redesigned Starbucks Rewards program and coffeehouse upgrades. Starbucks reported its fourth consecutive quarter of comparable store sales growth in its fiscal third quarter of 2026 (US comparable sales up 7.9%) and raised its full-year guidance.
Results have been uneven during the turnaround: operating margin fell to 7.9% in fiscal 2025 from 15.0% in fiscal 2024, including $892 million of restructuring and impairment charges (fiscal 2025 Form 10‑K). Rent increases and renewal options vary by lease, and renewals are at Starbucks’ option.
Investors evaluating Starbucks NNN properties should focus on location quality, lease terms, cap rate entry, and the tenant’s credit trajectory. This analysis examines Starbucks’s credit profile, lease structure, market positioning, and investment considerations as of October 2026.
Starbucks Credit Rating Analysis
For landlords, the rating applies when Starbucks Corporation is the tenant or guarantor on the lease; a corporate lease does not prevent a store from closing, but it determines who keeps paying rent if it does.
Investors should monitor Starbucks’s quarterly earnings releases, cash flow generation, and any changes in credit outlook. Credit ratings are agency opinions of an issuer’s credit, not of a specific lease, so property location and lease terms remain critical evaluation factors.
Starbucks NNN Lease Structure
Initial terms and renewal options vary by lease. Starbucks’ 10‑K says many of its real estate leases require it to pay certain expenses, such as common area maintenance, real estate taxes and other executory costs; a lease may leave roof, structure or parking lot costs with the landlord, so confirm expense responsibilities in each lease.
Rent increases vary by lease; confirm the rent schedule. Renewal options are at Starbucks’ discretion, and Starbucks’ 10-K says its leases often include options to extend or terminate at its sole discretion, so check for any early termination right.
Where Starbucks Corporation signs or guarantees the lease, its credit backs the rent for the lease term even if a location underperforms, unless the lease gives Starbucks an early termination right. Licensed Starbucks stores are run by licensed store operators (Form 10‑K), so Starbucks Corporation may not be the tenant; confirm the tenant entity named in each lease.
Starbucks NNN Cap Rate & Pricing Trends
Live asking cap rates for Starbucks and comparable tenants:
| Tenant | S&P / Moody’s | Median asking cap rate | Middle half of listings | Listings | Median vs. 10-year Treasury |
|---|---|---|---|---|---|
| McDonald's | BBB+ / Baa1 | 4.00% | 3.75% to 4.15% | 43 | −124 bps |
| Chick-fil-A | n/a / n/a | 4.22% | 4.00% to 4.50% | 45 | −102 bps |
| Dutch Bros | NR / NR | 5.50% | 5.25% to 5.60% | 96 | +26 bps |
| Starbucks | BBB+ / Baa1 | 5.75% | 5.35% to 6.19% | 118 | +51 bps |
Active listings InvestmentGrade.com tracks with an asking cap rate (stated in the listing, or computed from its stated income and price when no rate is stated), listings last observed October 12, 2026. Asking cap rates are not closed-sale cap rates. The middle half is the range from the 25th to the 75th percentile of listings. The 10-year Treasury yield is 5.24% as of October 1, 2026 (FRED series DGS10). Ratings are the agency ratings in our ratings database for the entity shown, which may be a parent company; the rating type (for example issuer, senior unsecured debt, long-term debt or revenue bond ratings) varies by company and is shown on each tenant page. A rating applies to a lease only if the rated entity signs or guarantees it, so confirm the tenant and any guarantor in the lease. n/a means no verified rating is on file.
Asking cap rates vary with location, building vintage, lease structure and remaining lease term. Asking cap rates are not closing cap rates.
In the listings InvestmentGrade.com tracks, the middle half of Starbucks asking prices runs from about $2.40M to $3.28M, with a median near $2.84M (prices vary with location, building quality and lease structure).
For how credit ratings and net lease pricing fit together, see our investment grade guide.
Starbucks Real Estate Footprint
Starbucks operated about 18,400 stores in North America as of June 28, 2026, including roughly 7,200 licensed locations. The footprint includes freestanding drive-through buildings, spaces in multi-tenant retail centers, and licensed locations inside other businesses. Single-tenant Starbucks net lease properties are often freestanding drive-through buildings on pad sites.
Starbucks Growth & Expansion Outlook
Starbucks is pruning its North American store base while it opens new stores. In fiscal 2025 it opened 509 and closed 620 US company-operated stores, according to its 10-K. On September 22, 2026, its board approved closing about 1% of its more than 18,000 North American coffeehouses (about 250 stores), mostly by the end of fiscal 2026, with about $300 million of restructuring charges, roughly $200 million of them in cash and primarily for lease exit costs and severance. Starbucks now expects about 440 net new global openings in fiscal 2026, down from prior guidance of 600 to 650.
For landlords, this means store-level performance matters even with a corporate tenant: a closing store may keep paying rent, negotiate an exit, or leave a dark building at lease end. Check store performance where available and the strength of the site for a replacement user. Our ratings database lists Starbucks Corporation as investment grade, and its turnaround has restored comparable sales growth.
Starbucks NNN Investment: Pros & Cons
| Pros | Cons |
|---|---|
| About 18,400 North American stores as of June 28, 2026 (Form 10‑Q) | Leases often include renewal or early termination options at Starbucks’ sole discretion (Form 10‑K) |
| Starbucks Corporation may sign or guarantee leases on company-operated stores (confirm per lease) | Union activity and labor cost pressures |
| Senior unsecured debt rated BBB+/Baa1 by S&P and Moody’s | Exposure to discretionary consumer spending |
| Back to Starbucks turnaround: four consecutive quarters of comparable store sales growth through fiscal Q3 2026 | Competition from other coffee concepts |
Comparable NNN Tenants
| Comparable Tenant | Rating | Investment Grade Status |
|---|---|---|
| McDonald’s | BBB+/Baa1 | Investment Grade |
| Chick-fil-A | no verified rating | Not Yet Verified |
| Dutch Bros | Not rated | Not Rated |
What is the credit rating of Starbucks?
Our ratings database shows Starbucks Corporation’s senior unsecured debt at BBB+ (S&P) and Baa1 (Moody’s), so its status is investment grade. In the pricing term sheet for its May 2025 note offering, both agencies had negative outlooks; we have not verified a later outlook, so check the current outlook in the ratings table.
What are asking cap rates for Starbucks NNN properties?
Current median asking cap rates for Starbucks and comparable tenants are shown in the live table on this page. Pricing for a specific property depends on the remaining lease term, rent level, location and lease guarantor, and asking cap rates are not closed-sale cap rates.
Is Starbucks a good NNN investment?
It depends on the property and the lease. Starbucks Corporation’s senior unsecured debt is rated BBB+/Baa1, but a specific property turns on who signs or guarantees the lease, the remaining term, the rent, any early termination right and how well the site would suit another user. Careful property selection and location analysis remain critical.
What lease terms do Starbucks NNN properties have?
Initial terms and renewal options vary by lease, and Starbucks’ 10‑K says its leases often include options to extend or terminate at its sole discretion. Review the rent schedule and any termination provisions in each lease.
When the buyer owns the building, a cost segregation study may reclassify part of the purchase price, such as site improvements and some building systems and equipment, into 5-, 7- or 15-year property. That property can qualify for 100% bonus depreciation under Internal Revenue Code section 168(k) if acquired and placed in service after January 19, 2025 (IRS Notice 2026‑11). How much qualifies varies widely by property and must be supported by an engineering-based study. On a ground lease the investor owns only land, which cannot be depreciated, and equipment owned by the tenant is not the landlord’s to depreciate. Bonus depreciation is generally recaptured as ordinary income on a taxable sale (Internal Revenue Code sections 1245 and 1250); a 1031 exchange can defer it, subject to the limits in sections 1245(b)(4) and 1250(d)(4). In restaurants and auto service buildings, kitchen, drive-through and service equipment may be owned by the tenant; confirm in the lease. This is general information, not tax advice; consult a tax professional. See the QSR and Auto Service NNN Depreciation Guide.
Starbucks Net Lease Property: Buying, Selling and Financing
Buying: We find on-market and off-market Starbucks properties, review the lease and the tenant’s credit, and compare pricing with current listings. On the majority of transactions, there is no separate fee to you as the buyer; the listing broker pays a cooperating commission.
Selling: We can prepare an opinion of value from current listings and recent sales and, when it fits your goals, run a confidential sale to private investors, family offices and institutional buyers. See our guide to off-market sales.
Financing: Investment Grade Capital, a service of Investment Grade LLC, matches buyers and owners with lenders for acquisitions and refinancing.
1031 exchanges: Tell us your identification and closing deadlines so we can plan the search around them.
Request an NNN investment consultation or email team@investmentgrade.com.
Related NNN Tenants
Compare Starbucks against current NNN cap rates
Before underwriting a Starbucks net lease, benchmark the asking cap rate against the broader 2026 NNN cap rates by tenant credit quality so the spread reflects both Starbucks credit risk and lease structure.
Starbucks NNN Properties Observed For Sale
124 active Starbucks net lease listings observed across public listing sources, most recently Oct 12, 2026. Asking figures as published by the listing party.
| Location | Asking Price | Cap Rate | Building SF | Term Left | |
|---|---|---|---|---|---|
| Kissimmee, FL | $3,500,000 | 5.00% | 3,513 | n/a | View listing |
| Huntsville, AL | $2,821,000 | 6.00% | 2,475 | n/a | View listing |
| Laurens, SC | $2,618,000 | 6.00% | 2,281 | n/a | View listing |
| Sumter, SC | $2,112,000 | 6.00% | 2,500 | n/a | View listing |
| Grand Forks, ND | $2,950,000 | 6.21% | 2,262 | 8.9 yrs | View listing |
| Billings, MT | $3,600,000 | 5.50% | 2,448 | n/a | View listing |
| Wells, ME | $3,000,000 | 6.00% | 2,500 | n/a | View listing |
| Garden City, ID | $2,600,000 | 5.80% | 1,166 | 8.8 yrs | View listing |
Search all 124 observed Starbucks listings and the full NNN inventory
Market observations aggregated from listing broker materials; not offerings by Investment Grade Income Property, LP. Buyer representation available on a cooperating commission basis. Information deemed reliable but not guaranteed.
